A beneficial owner is a person whose ownership or control matters under a particular legal or commercial standard. A bank, buyer, or compliance team may use the term for different purposes. Therefore, the first step is to identify which definition applies to the request.
The answer rarely comes from one public search. State filings can help establish an entity’s identity and history, while company records may explain equity and voting rights. However, the available evidence and disclosure requirements vary with the entity and jurisdiction.
Compliance Officers helps assess ownership structures and organize supporting evidence. This guide explains the CDD Rule, BOI reporting, OFAC ownership restrictions, and the records a commercial review may need. It also identifies conclusions that a registration certificate or customer declaration cannot establish by itself.
Which beneficial owner definition applies?
Different rules use ownership and control for different purposes. Under the federal CDD Rule, covered financial institutions identify beneficial owners of relevant legal entity customers. The rule contains an ownership test and a separate control test, along with exclusions and exemptions.
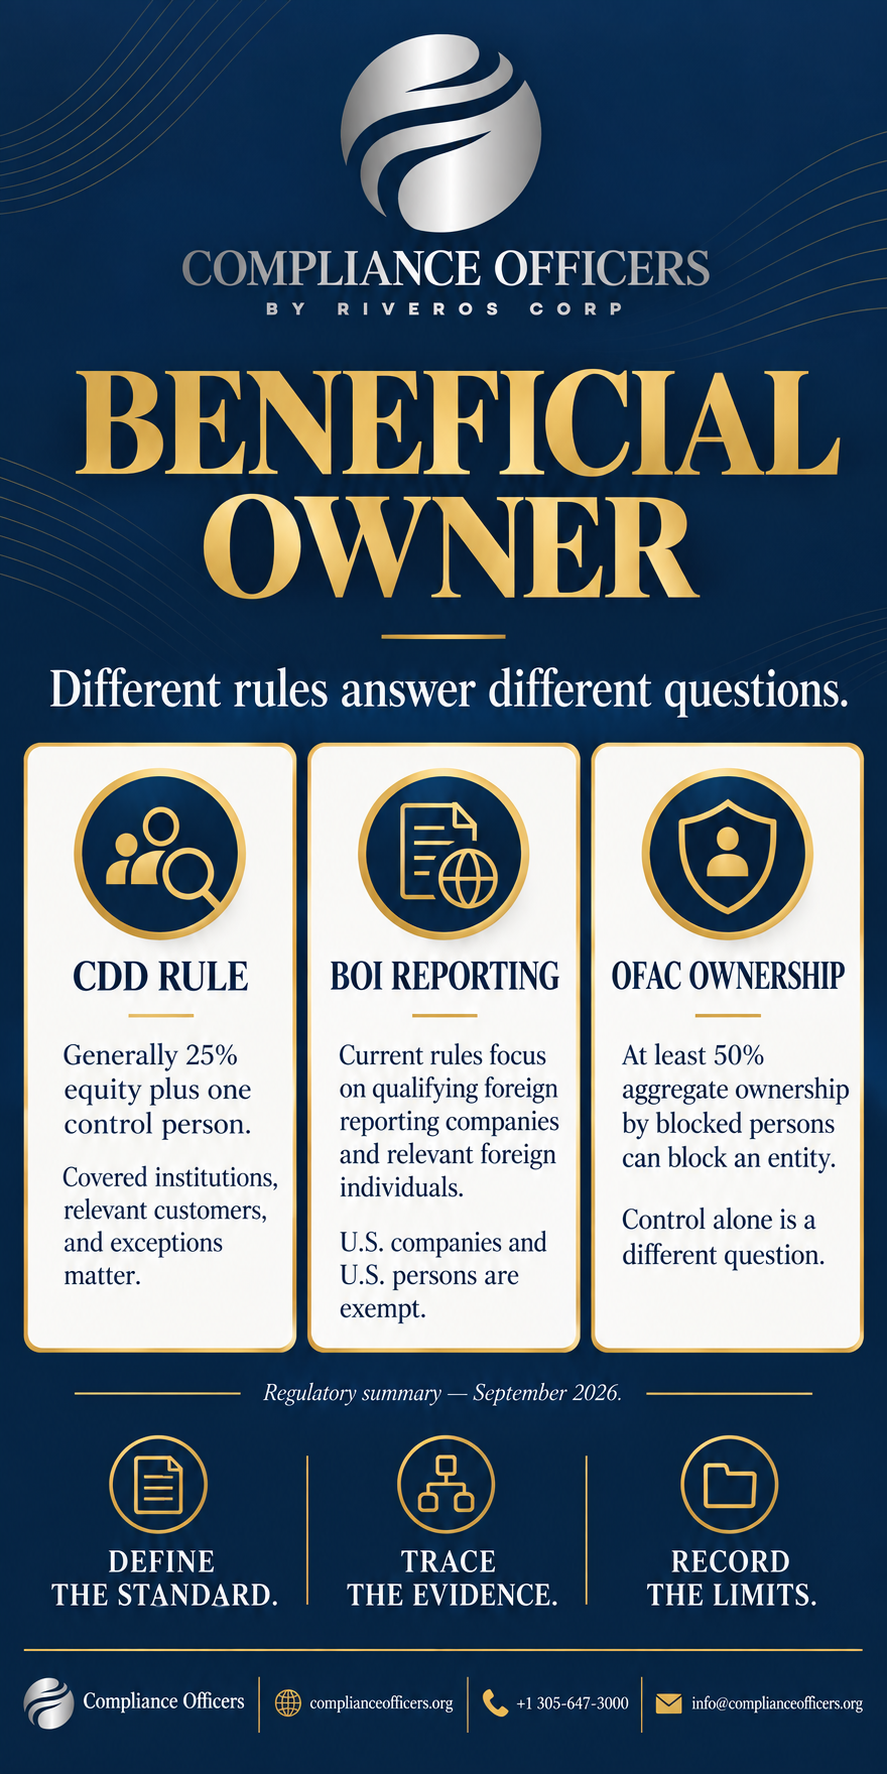
BOI reporting under the Corporate Transparency Act is another system. It concerns filings by entities that qualify as reporting companies. Meanwhile, OFAC’s 50 Percent Rule determines when ownership by blocked persons causes an entity to be blocked.
A commercial review may ask broader questions about who benefits, votes, appoints management, or can direct a transaction. Consequently, a response that satisfies one regulatory threshold may leave another business question unanswered. The requested scope should state the standard and the decision it supports.
The CDD Rule's beneficial owner tests
The CDD Rule covers banks, securities brokers or dealers, mutual funds, futures commission merchants, and introducing brokers in commodities. Its requirements apply within the rule’s defined customer and account scope. An ordinary operating company does not become a covered institution merely because a bank requests its ownership information.
However, the bank may need that company’s cooperation to meet its own obligations. The company may also face separate sanctions, contractual, or sector-specific requirements. Our explanation of the FinCEN CDD Rule describes that distinction.
Ownership and control work separately
For a customer subject to both tests, the ownership prong generally identifies each individual with at least 25 percent of its equity. Direct and indirect interests count. Depending on the structure, this can produce up to four individuals or none, subject to the trust provisions.
The control prong identifies one individual with significant responsibility to control, manage, or direct the entity. That person may also meet the ownership test. However, a convenient signatory is not necessarily the appropriate control person.
For example, four individuals could each hold 24 percent, while a fifth holds 4 percent. No individual then reaches the ownership threshold solely through those stated interests. The control test still requires an appropriate individual where it applies.
Trusts and exclusions need separate attention
If a trust holds at least 25 percent of the relevant customer’s equity, the CDD ownership provision identifies the trustee. FinCEN’s guidance permits an entity trustee in that role. Also, for multiple trustees, it expects identification and identity verification of at least one, with additional review depending on risk.
Exclusions can change the analysis. For example, certain entities fall outside the defined customer category, while qualifying nonprofits generally require the control prong without the ownership prong. Therefore, a statement that every entity must always name the same set of people would be inaccurate.
Identifying a beneficial owner and verifying identity
Identifying who meets the definition differs from verifying that person’s identity. The CDD Rule requires covered institutions to use appropriate procedures for identity verification. However, it does not require independent investigation of every ownership structure in every case.
FinCEN permits reasonable reliance on ownership-status information from the customer’s representative when no known facts reasonably undermine its reliability. A certification can therefore serve a legitimate regulatory purpose. It should not automatically be dismissed as useless or described as independent proof of the entire structure.
If information conflicts or reliability concerns arise, the institution needs to address them under the applicable requirements. A commercial buyer may also choose deeper corroboration for its own decision. That additional scope should remain distinct from the regulatory minimum.
Beneficial owner review after the 2026 CDD relief
FinCEN’s February 13, 2026 order permits covered institutions to limit repeated identification and identity verification under specified conditions. The relevant scenarios include the customer’s first account, later reliability concerns, and review required by risk-based ongoing procedures.
This relief does not remove the CDD Rule’s ownership and control definitions. Nor does it eliminate other AML obligations. Institutions may also continue using the prior account-opening approach if they choose.
For certain ongoing-review situations, the order permits reliance on previously obtained information when the customer confirms that it remains current. The institution must retain a record of that confirmation. However, this is not a blanket rule requiring a fresh confirmation at every additional account opening.
BOI reporting and beneficial owner information
FinCEN announced its final BOI rule on August 11, 2026, with effectiveness upon publication on August 14. The rule permanently exempts U.S. companies and U.S. persons from BOI reporting requirements under the current framework.
Foreign entities that qualify as reporting companies still have duties concerning their foreign individual beneficial owners. The applicable reporting definition addresses substantial control and ownership of at least 25 percent, subject to its provisions. It is separate from the CDD test that requires one control person.
The final rule also addresses U.S.-person company applicants and certain update or correction duties associated with FinCEN identifiers. It directs deletion of information reasonably believed to relate to U.S. persons. An announcement of that direction should not be described as proof that all deletion has already occurred.
The BOI database is not a public directory
BOI information is not available for unrestricted public company searches. However, the access framework permits specified recipients and uses, including eligible financial institutions subject to consent and safeguards. It is therefore too broad to say that no private institution can ever receive BOI.
Likewise, the domestic reporting exemption does not mean that no federal record contains ownership information about any U.S. company. Other reporting systems may hold relevant information within their scope. The practical point is that there is no complete public federal directory answering every company’s ownership question.
OFAC ownership restrictions use a different test
Under OFAC’s 50 Percent Rule, an entity can be blocked through direct or indirect ownership by one or more blocked persons. The threshold is at least 50 percent in the aggregate. The entity need not appear separately by name on the sanctions list.
For example, two blocked persons holding 25 percent each directly in the same company reach that threshold together. A name search for the company alone may miss the resulting restriction. Consequently, ownership information can affect sanctions compliance beyond an immediate list match.
U.S. persons and businesses must comply with applicable sanctions restrictions. OFAC may impose civil penalties on a strict-liability basis, even without knowledge of a violation. Nevertheless, the program, transaction, jurisdiction, exemptions, and authorizations affect the analysis.
Control alone is not the same as 50 percent ownership
OFAC’s ownership rule does not automatically block an entity solely because a blocked person controls it without the required ownership interest. However, OFAC urges caution in such cases, and other restrictions may apply. Transactions involving the blocked person can raise separate issues.
Indirect ownership also requires the correct method. The analysis should follow OFAC’s guidance through the relevant entities, rather than mechanically reuse a CDD ownership calculation. A private report cannot authorize otherwise prohibited dealings.
Compare the three ownership frameworks
The comparison below explains why one answer may not fit every request. Each framework contains further definitions and exceptions. The review should apply those details to the actual entity and relationship.
| Framework | Main question | Relevant distinction |
|---|---|---|
| CDD Rule | Who meets the ownership and control tests for a covered customer’s file? | Generally 25 percent equity plus one control person, subject to scope and exceptions |
| CTA / BOI reporting | Which information must an in-scope reporting company file? | Current obligations focus on qualifying foreign entities and relevant foreign individuals |
| OFAC 50 Percent Rule | Does blocked-person ownership cause the entity to be blocked? | At least 50 percent aggregate direct or indirect ownership under OFAC’s method |
Records that support a beneficial owner review
State formation filings and current status records help identify the entity. Depending on the jurisdiction, they may list officers, managers, or other relevant information. However, a registered agent or listed manager is not necessarily an equity owner.
Company records can add details that public filings omit. Relevant material may include operating agreements, stock or membership registers, transfer records, and documents concerning intermediate entities. The evidence should connect the parties and interests identified in the review.
Our guide to assessing U.S. company records explains source limitations. A status certificate may support a finding about registration, but it does not establish every ownership interest, contractual right, or financial fact.
Follow each material layer
A company may hold its interest through another entity, which has its own owners. Such structures can serve ordinary business purposes. Therefore, the presence of several layers does not by itself establish concealment or misconduct.
The review should identify the links relevant to its standard and record the evidence for each one. If a layer remains unresolved, the report should explain how that gap affects the conclusion. An incomplete chain should not appear as a fully verified structure.
Control beyond the equity column
Equity percentages may not explain every important decision right. Voting agreements, appointment rights, management contracts, or particular share classes can affect control. Nevertheless, the legal significance of each right depends on the applicable test and the actual terms.
For example, a lender’s protective covenant does not automatically make it the controlling party for every purpose. Similarly, a person’s title alone may not establish significant management responsibility. The review should examine what the documents and operating facts support.
Trust and nominee arrangements require comparable care. Legal title, economic benefit, and authority may sit with different parties. The report should describe those roles accurately and apply the relevant definition, rather than assume that all roles produce the same beneficial owner.
Current evidence matters
Private transfers or amendments can change ownership without an immediate public filing. Consequently, the date of the records matters. A review for a current transaction should assess whether older documents still describe the relevant structure.
Where appropriate, updated representations and supporting records can address that question. The file should distinguish the date of a document from the date of the conclusion. It should also explain any change that remains unconfirmed.
Common beneficial owner review mistakes
One mistake is treating the absence of a 25-percent owner as the end of every inquiry. That answer may address one ownership test while leaving control, sanctions, or commercial concerns unresolved. Another is identifying someone merely because that person signed the account form.
Also, an earlier BOI filing acknowledgment does not independently prove that every submitted statement was correct or remains current. Its evidentiary value depends on what it actually records. The current domestic reporting exemption does not transform an old filing into a verified ownership opinion.
Finally, a report should avoid promising that every bank or buyer will accept the same file. Different recipients may require different evidence or procedures. Our discussion of customer review requirements provides related context.
How Compliance Officers supports the review
Compliance Officers helps define the ownership question, identify relevant entities, and organize the available records. The work can address ownership chains, control documents, and sanctions-related concerns within an agreed scope.
The resulting file can record sources, dates, supported findings, and unresolved matters. Where foreign records require translation or authentication, the team can coordinate those requirements. However, certification of a document does not independently verify every underlying ownership statement.
Timing depends on the structure, jurisdictions, access to records, and cooperation from relevant parties. Much of the coordination can occur remotely, but some steps may require client participation. The team cannot guarantee a receiving institution’s approval or eliminate every compliance risk.
Beneficial owner: frequently asked questions
Can one public search identify every owner?
No single public search provides a complete ownership file for every U.S. company. Public records may help, but company documents and other evidence can be necessary. The search scope should reflect the applicable definition and the transaction.
Do domestic U.S. companies still file BOI reports?
FinCEN’s August 2026 final rule exempts U.S. companies and U.S. persons under the current framework. Qualifying foreign reporting companies retain relevant obligations. However, the BOI exemption does not remove separate CDD or sanctions requirements.
Does the CDD Rule require a full independent investigation?
Not in every case. FinCEN permits reasonable reliance on customer-provided ownership-status information absent known reliability concerns. Covered institutions must still verify the relevant identities under their procedures and address issues requiring further review.
Is the CDD control person always an equity owner?
No. The ownership and control tests are separate. An appropriate high-level individual may meet the control test without owning equity. Also, someone who meets the ownership test may serve as the control person if the facts support both roles.
Does control by a blocked person always trigger OFAC's 50 Percent Rule?
Control alone does not trigger that ownership rule without the required ownership interest. However, OFAC urges caution, and other restrictions may apply. The business should assess the blocked person’s role and the proposed transaction carefully.
What affects the scope and timing of a review?
The number of ownership layers, jurisdictions, available records, and unresolved discrepancies affect the work. Translation or authentication may add further steps. Therefore, the initial assessment should identify the applicable standard and the evidence needed.
Discuss the ownership question
Contact Compliance Officers to discuss the company, ownership structure, and purpose of your review. Call +1 305-647-3000, use WhatsApp, or email info@complianceofficers.org. The team can assess the proposed scope and relevant record requirements.
This publication provides general information and does not constitute legal advice. Requirements depend on the entity, relationship, and applicable law. Professional support cannot guarantee acceptance of a file or authorize a prohibited transaction.