Company due diligence helps you assess the business behind a contract, invoice, or proposed transaction. The questions may concern legal existence, ownership, financial exposure, or signing authority. A useful review defines those questions first and then identifies the records that can answer them.
U.S. corporate information sits across state and other record systems. A company search may confirm a registration while leaving ownership, operations, and financial condition unresolved. Consequently, a review should explain what each result supports and what still needs clarification.
Compliance Officers helps assemble and assess those records for a defined transaction. The sections below explain the main sources, their limits, and the issues that can affect a company file. They also distinguish a commercial review from particular regulatory obligations.
Company due diligence across U.S. record systems
Ordinary U.S. corporations and LLCs generally form under state law. The relevant filing office may be a Secretary of State, Division of Corporations, Corporation Commission, or another designated authority. Also, states use different search systems and terminology.
Some offices issue a certificate of good standing; others use terms such as certificate of existence or status. Therefore, the certificate’s actual wording and applicable law determine its meaning. A reviewer should avoid assuming that every state certifies precisely the same matters.
There is no single public registry that provides a complete legal and financial file for every U.S. business. State records, court files, licensing information, and relevant federal records answer different questions. A national commercial search product may help locate material, but its coverage and update cycle still need assessment.
Federal records in company due diligence
An Employer Identification Number identifies a business for federal tax administration. It does not, by itself, prove good standing, tax compliance, ownership, or the authority of a person contacting you. Similarly, SEC filings can provide useful information for entities within that reporting system, but do not cover every private business.
FinCEN’s BOI database is not a public company-ownership directory. In August 2026, FinCEN finalized exemptions for U.S. companies and U.S. persons and announced deletion of previously reported U.S.-person information. Qualifying foreign reporting companies still have reporting duties concerning relevant foreign individuals.
Therefore, a review cannot assume that a public FinCEN search will establish the owners of a U.S. counterparty. Company records and other appropriate evidence may be necessary. Our guide to beneficial ownership and control explains why those concepts require separate attention.
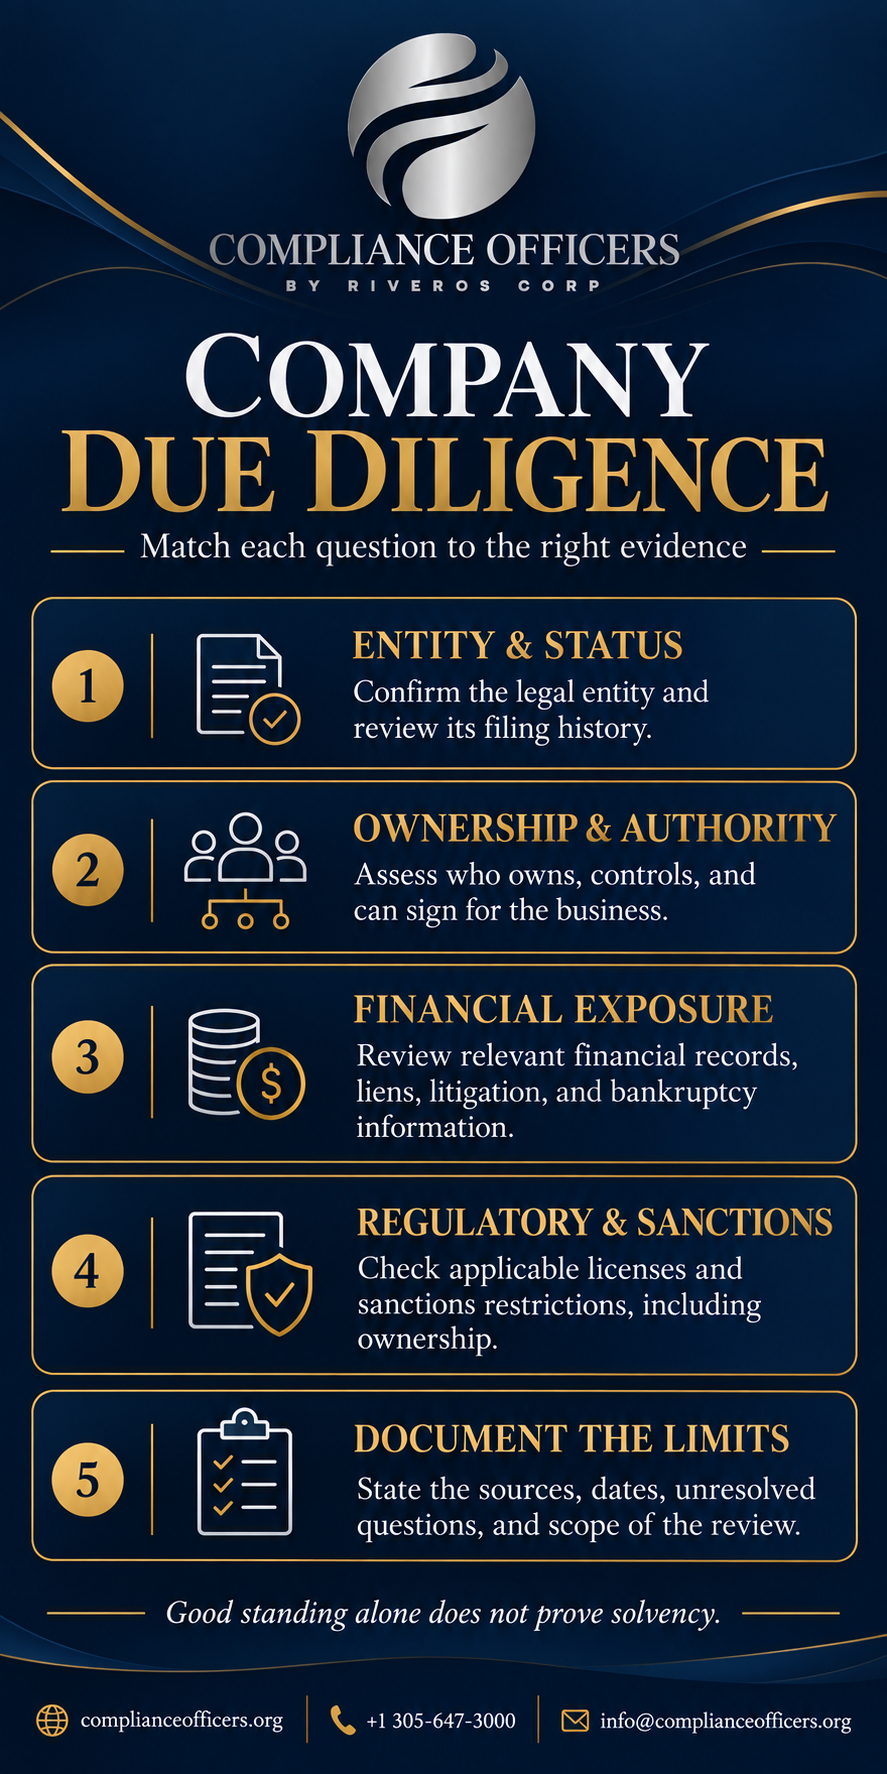
What company due diligence sources establish
A record should support the conclusion attributed to it. For example, a formation filing and a current financial statement address different issues. The comparison below summarizes the main uses and limitations of common sources.
| Source | What it can support | Principal limitation |
|---|---|---|
| State formation records | Legal name, entity number, formation date, and recorded history | They do not alone establish solvency or actual operations. |
| Status certificate | The matters the issuing office certifies on the stated date | It does not certify financial condition or later developments. |
| Foreign qualification records | Registration to do business in the relevant state | They do not establish compliance in every other jurisdiction. |
| EIN or relevant IRS records | Tax identity or the specific status the record confirms | An EIN alone does not establish tax compliance. |
| UCC financing statements | Notice of claimed security interests and described collateral | They do not show all debt or prove the current debt balance. |
| Court dockets | Located proceedings, filings, and recorded outcomes | Coverage, sealed records, and private proceedings limit the search. |
| Licensing records | Recorded authorization and discipline within that regulator’s scope | A license for one activity does not cover every service. |
| Sanctions information | Applicable designations and restrictions | A name search alone may miss ownership-based blocking. |
| Federal agency records | Relevant records the agency holds and discloses | Availability, exemptions, and response time limit access. |
Legal identity and company due diligence
First, establish which entity will enter the transaction. A business group may use separate entities for operations, intellectual property, property ownership, or payment collection. However, similar names do not establish that the entities are interchangeable.
The proposed contract, invoice, and payment instructions should identify the relevant parties consistently. If an affiliate or agent will receive payment, the arrangement needs a clear explanation and appropriate supporting authority. A legitimate group structure can involve different entities, but that distinction must remain visible.
Entity numbers and formation jurisdictions help distinguish namesakes. For example, a trade name or website brand may differ from the legal name. As a result, a search under a marketing name alone can miss the relevant record or return a different company.
Registered agents and operating addresses
A registered agent receives specified legal notices and service of process. For example, the agent’s address may belong to a commercial provider. It does not necessarily identify the company’s office, staff, or place of operations.
Likewise, a virtual-office address does not by itself prove misconduct. It does mean that the address alone cannot establish operational capacity. The review should seek evidence relevant to the promised service or transaction. Our corporate document checklist discusses related file questions.
Formation history and foreign qualification
A current status screen may not explain earlier name changes, mergers, conversions, dissolution, or reinstatement. Those events can affect the continuity of a search and the interpretation of older records. Consequently, a review may need relevant filing history as well as current status.
However, a missing search result also requires care. The wrong jurisdiction, a former name, or a search-system limitation can explain it. A reviewer should resolve the identity question before treating an unsuccessful search as proof that the company does not exist.
Companies may form in one state and conduct business in another. Depending on their activities and the relevant law, they may need foreign qualification in the operating state. Formation elsewhere is common and does not, by itself, indicate a problem.
Consequences depend on the applicable state law
Failure to obtain required authority can lead to penalties or restrictions on maintaining a court action. However, it does not universally invalidate contracts. For example, Florida law preserves a foreign corporation’s contracts despite failure to qualify, while restricting its ability to maintain an action until it obtains authority.
Therefore, the review must identify the entity type, activities, and governing jurisdiction. A legal conclusion about enforceability needs more than a registration search. Counsel should assess that question where it matters to the transaction.
Financial exposure in company due diligence
Active status or good standing does not establish that a company can pay its debts. Instead, financial condition requires evidence relevant to assets, liabilities, cash flow, and the proposed commitment. Public records can reveal concerns, but they do not supply a complete financial assessment.
A UCC financing statement gives notice concerning a claimed security interest. However, its presence does not necessarily establish a current debt balance or the enforceability of a lien. Likewise, the absence of a located filing does not prove that all assets are unencumbered.
The appropriate jurisdiction and debtor name affect UCC research. For many registered organizations, the state of organization is central to the analysis. However, collateral-specific rules and other exceptions may require a different filing office or additional review. A trade-name search alone may be insufficient.
Court and bankruptcy records
Court records may identify litigation, judgments, injunctions, or bankruptcy proceedings. However, their meaning depends on the parties, allegations, procedural history, and outcome. For example, a complaint contains allegations; it does not establish those allegations as facts.
Also, court systems differ in coverage and public access. Sealed matters, private arbitration, and certain settlements may not appear in ordinary public searches. A report should state its search scope and avoid describing an incomplete search as universal clearance.
Licensing and sanctions review
A company’s registration and its permission to perform regulated work are separate issues. Therefore, a licensing review should match the legal entity, activity, location, and relevant regulator. The scope of a particular license matters as much as whether a record exists.
Sanctions obligations also require separate attention. U.S. persons and businesses must comply with applicable OFAC restrictions. OFAC may impose civil penalties on a strict-liability basis, even without knowledge that a transaction violated a prohibition. The applicable program, jurisdiction, exemptions, and authorizations still matter.
OFAC’s 50 Percent Rule can block an entity that does not appear by name on a sanctions list. It concerns direct or indirect ownership of at least 50 percent in the aggregate by one or more blocked persons. Therefore, ownership can affect a sanctions assessment beyond the immediate name match.
A risk-based sanctions process should consider the transaction and relevant parties. This differs from claiming that every business must use an identical screening tool or checklist. The review should explain applicable restrictions and escalate unresolved matches or ownership concerns appropriately.
Federal records and timing
Some files need federal agency records beyond material already available online. The Freedom of Information Act provides a request process for agency records, subject to exemptions and other legal limits. However, it is not an instant search service or a guarantee of disclosure.
Response time depends on the request, the agency, and the records involved. A statutory response deadline does not necessarily mean the requester will receive every document by that date. Confidential business information, privacy, and other protected interests may limit disclosure.
Our explanation of the FOIA process addresses those limitations. If federal records may affect a transaction, their potential timing should form part of the initial scope discussion.
Common company due diligence mistakes
One mistake is reviewing a well-known parent while the contract names a different affiliate. Another is relying on a screenshot without assessing the issuing source and date. In both situations, a seemingly complete file can answer the wrong question.
Commercial databases also need context. They may help locate records, but update cycles and entity matching can affect results. Therefore, material findings should tie back to a suitable source rather than rely solely on an unexplained summary.
A further mistake is using the same scope for every decision. A small purchase, a credit relationship, and an acquisition can expose the client to different risks. Accordingly, the review should match the decision, the available evidence, and any applicable legal duties.
Record gaps without hiding their significance
A report should distinguish a confirmed finding from an unresolved issue. It should also explain the date and scope of the records reviewed. That lets the reader understand whether further work could change the decision.
Our guide to a source-supported due diligence report explains this approach. A clear record of limitations is more useful than an unsupported statement that a company is fully cleared.
How Compliance Officers supports company due diligence
Compliance Officers helps define the review around the counterparty and proposed transaction. The work may cover corporate existence and history, ownership and control, relevant registrations, liens and disputes, or regulatory and sanctions information.
The team can organize the findings into an English-language report with source references, dates, and unresolved questions. If documents need translation or authentication, those requirements should form part of the agreed scope. Such services support the review but do not establish every underlying statement as true.
Much of the coordination can take place remotely. However, record availability and issuing-office requirements affect delivery. The team can identify those constraints and coordinate follow-up. It cannot promise a particular authority’s response time, financing approval, or a transaction’s outcome.
Company due diligence: frequently asked questions
Is there one website that verifies any U.S. company?
No single public website supplies a complete file for every U.S. business. Different sources address registration, financial exposure, licensing, and sanctions. The appropriate combination depends on the entity and the purpose of the review.
Does good standing prove solvency?
No. A status certificate confirms the matters stated by its issuing office on the relevant date. It does not prove financial condition, available assets, or ability to perform a contract.
How long does a review take?
Timing depends on scope, jurisdictions, record availability, and any translation or authentication requirements. Federal record requests and substantive court review may add time. The initial assessment should identify likely constraints.
Must a business perform the same checks as a bank?
The federal CDD Rule applies to covered financial institutions. Ordinary businesses may have different duties, including applicable sanctions obligations and sector-specific requirements. Their review should reflect those duties and the transaction’s risks.
What determines the service scope?
The entities, jurisdictions, financial exposure, and evidence gaps determine the work. A defined scope should explain which records and checks it includes. Contact Compliance Officers to assess the requirements of your transaction.
Is a recently formed company automatically a concern?
Recent formation warrants context rather than an automatic adverse conclusion. A transaction may use a new special-purpose entity. The review should assess its role, authority, resources, and any relevant support from other parties.
Discuss the company and transaction
Contact Compliance Officers to review your counterparty and the decision you need to make. Call +1 305-647-3000, use WhatsApp, or email info@complianceofficers.org. The team can assess the available documents and explain the proposed scope.
This publication provides general information and does not constitute legal or financial advice. The appropriate review depends on the transaction and applicable law. Professional support cannot guarantee a counterparty’s future conduct or financial performance.