Enhanced due diligence is a more detailed review of a customer, counterparty, or relationship when its risks require closer examination. It may involve additional ownership research, source-of-funds information, or analysis of activity that the existing file does not explain.
The scope should follow the question that needs an answer. For example, a company may exist and appear in good standing while providing little information about its owners. A name search alone will not resolve that uncertainty.
Compliance Officers provides documented research to support these reviews. The work helps clients assess available evidence and identify unresolved issues. It does not guarantee a particular decision by a bank, regulator, or other recipient.
How enhanced due diligence relates to ordinary CDD
Customer due diligence already extends beyond identifying a name or confirming incorporation. For banks, it includes understanding the nature and purpose of a relationship and conducting ongoing monitoring under the applicable requirements.
Enhanced due diligence builds on that work when greater scrutiny is appropriate. It can require more detail or corroboration about a specific risk. The distinction concerns the depth and focus of the review, not a universal divide between “identity checks” and “real investigation.”
For example, an ownership chart may show several holding companies. Additional research may help establish who owns them and whether the structure affects sanctions exposure. The existence of multiple entities is not, by itself, proof of misconduct.
Our explanation of the CDD rule and its requirements covers the financial-institution framework. A commercial business should identify its own obligations before adopting a bank’s terminology or procedures.
When the law requires closer scrutiny
Certain U.S. financial-sector rules expressly require enhanced measures. Under 31 CFR 1010.610, covered correspondent relationships with foreign financial institutions require due diligence. Specified categories of foreign banks also trigger enhanced due diligence requirements.
Another rule, 31 CFR 1010.620, governs qualifying private banking accounts for non-U.S. persons. It requires enhanced scrutiny when a senior foreign political figure is a nominal or beneficial owner, aimed at detecting and reporting possible proceeds of foreign corruption.
The private banking definition has several elements. It includes a required minimum aggregate deposit of at least $1 million, a non-U.S. owner or beneficiary, and a bank liaison. A high balance alone does not establish that the account falls within that definition.
These are examples of specific obligations, not a complete list of circumstances requiring additional review. Banks also need risk-based CDD procedures for higher-risk relationships. Other sectors and jurisdictions may impose different requirements.
What can trigger enhanced due diligence?
A trigger should identify a concern that deserves examination. It should not stand in for a conclusion. A newly formed company, a virtual address, or an international ownership structure can have a legitimate explanation.
Possible reasons for a closer review include inconsistent ownership information, unexplained transaction patterns, relevant sanctions exposure, or credible adverse information. The significance depends on the relationship and the available evidence.
| Information in the file | Question for further review |
|---|---|
| Ownership ends at another company | What additional ownership information is relevant and available? |
| Payments differ from the stated business activity | What explains the activity and its funding? |
| A possible sanctions match appears | Does the match concern this person or entity, and do restrictions apply? |
| A report describes alleged misconduct | Is the subject the same, what is the source, and what is the current status? |
Likewise, a refusal to answer a question may leave a material gap, but it does not prove wrongdoing. Consider the request, its relevance, and any explanation. Then decide what the unresolved gap means under the applicable rules and policy.
Ownership research and its limits
An enhanced due diligence review may need to follow an ownership chain beyond the first registered shareholder. The required depth depends on the purpose, governing rules, and identified risks.
A state filing can help confirm legal existence or identify certain officers. However, it may not disclose every owner or the current ownership percentages. Treat each record according to what it actually establishes.
Private corporate records and information supplied by the counterparty may also be relevant. Their reliability still requires assessment. An unsigned chart or an old register may leave questions about the present structure.
Our guide to the beneficial owner of a legal entity explains why different legal frameworks use different definitions. Do not assume that a threshold used for one rule resolves every ownership question.
If the research cannot establish a material fact, record that limit. A clear statement of an unresolved issue is more useful than an unsupported claim that the ownership is fully verified.
Source of funds and source of wealth
A source-of-funds review examines the money involved in a particular transaction or relationship. Source of wealth concerns how a person accumulated assets over time. The two questions can overlap, but they are not interchangeable.
For example, a payment may come from a named bank account. That identifies its immediate route, but may not explain the activity that generated the money. Conversely, a history of business ownership may explain wealth without identifying the funds for a specific transaction.
The review should connect the explanation to relevant evidence. The appropriate records depend on the transaction and the risk. There is no single document that proves every source-of-funds explanation.
Also avoid treating an unfamiliar business model as inherently suspicious. The question is whether the available facts support a coherent account of the activity. Where evidence is missing or inconsistent, the report should explain what remains uncertain.
Sanctions analysis within enhanced due diligence
Sanctions obligations are separate from the CDD rule. Being outside a particular financial-institution rule does not remove sanctions restrictions that otherwise apply to a person or transaction.
OFAC’s 50 Percent Rule is relevant to ownership analysis. An entity owned 50 percent or more, directly or indirectly and in the aggregate, by blocked persons is itself blocked. Its name does not have to appear separately on a sanctions list.
Therefore, a list search can leave an important gap if the ownership requires examination. The analysis must also distinguish blocking sanctions from other types of restrictions. Not every list entry has the same consequences.
OFAC may impose civil penalties on a strict-liability basis for sanctions violations. A person subject to U.S. jurisdiction can face liability without knowing that the transaction was prohibited. However, that does not mean every business must use one prescribed screening product or identical screening frequency.
If a restriction may apply, obtain an appropriate sanctions assessment before proceeding. Additional documents or a favorable commercial risk decision cannot authorize a prohibited transaction.
Politically exposed persons require context
A politically exposed person, or PEP, is not automatically a sanctioned person. Political exposure and sanctions address different issues. The review should identify the relevant role, relationship, and applicable legal framework.
U.S. banking agencies have explained that PEP status alone does not make every customer high risk. The CDD rule does not impose a unique set of additional steps solely because a customer is a PEP. The relationship’s actual risk remains relevant.
At the same time, the specific private banking rule for senior foreign political figures still applies where its conditions are met. That defined category should not be treated as identical to every use of “PEP” in a screening database.
For an individual review, assess the facts rather than rely on the label. The person’s position, access to public resources, activity, and relevant jurisdictions may help explain the concern. A match should lead to a reasoned assessment, not an automatic allegation.
Possible matches and adverse information
A screening alert is a candidate match. It may identify the counterparty, or it may concern someone with a similar name. Neither outcome should be assumed before reviewing the available identifiers.
Relevant details can include a date of birth, registration number, location, or other distinguishing information. Transliteration and trading names can complicate the comparison. Record the basis for resolving a match or leaving it unresolved.
Adverse information needs similar care. Distinguish an allegation, an investigation, a filed charge, and a final judgment. Also consider whether later developments change the meaning of an older report.
Research in relevant languages can improve coverage, but no language or database captures every event. An absence of results means that the defined research found no relevant results. It is not proof that the subject has never faced an issue.
What an enhanced due diligence report should explain
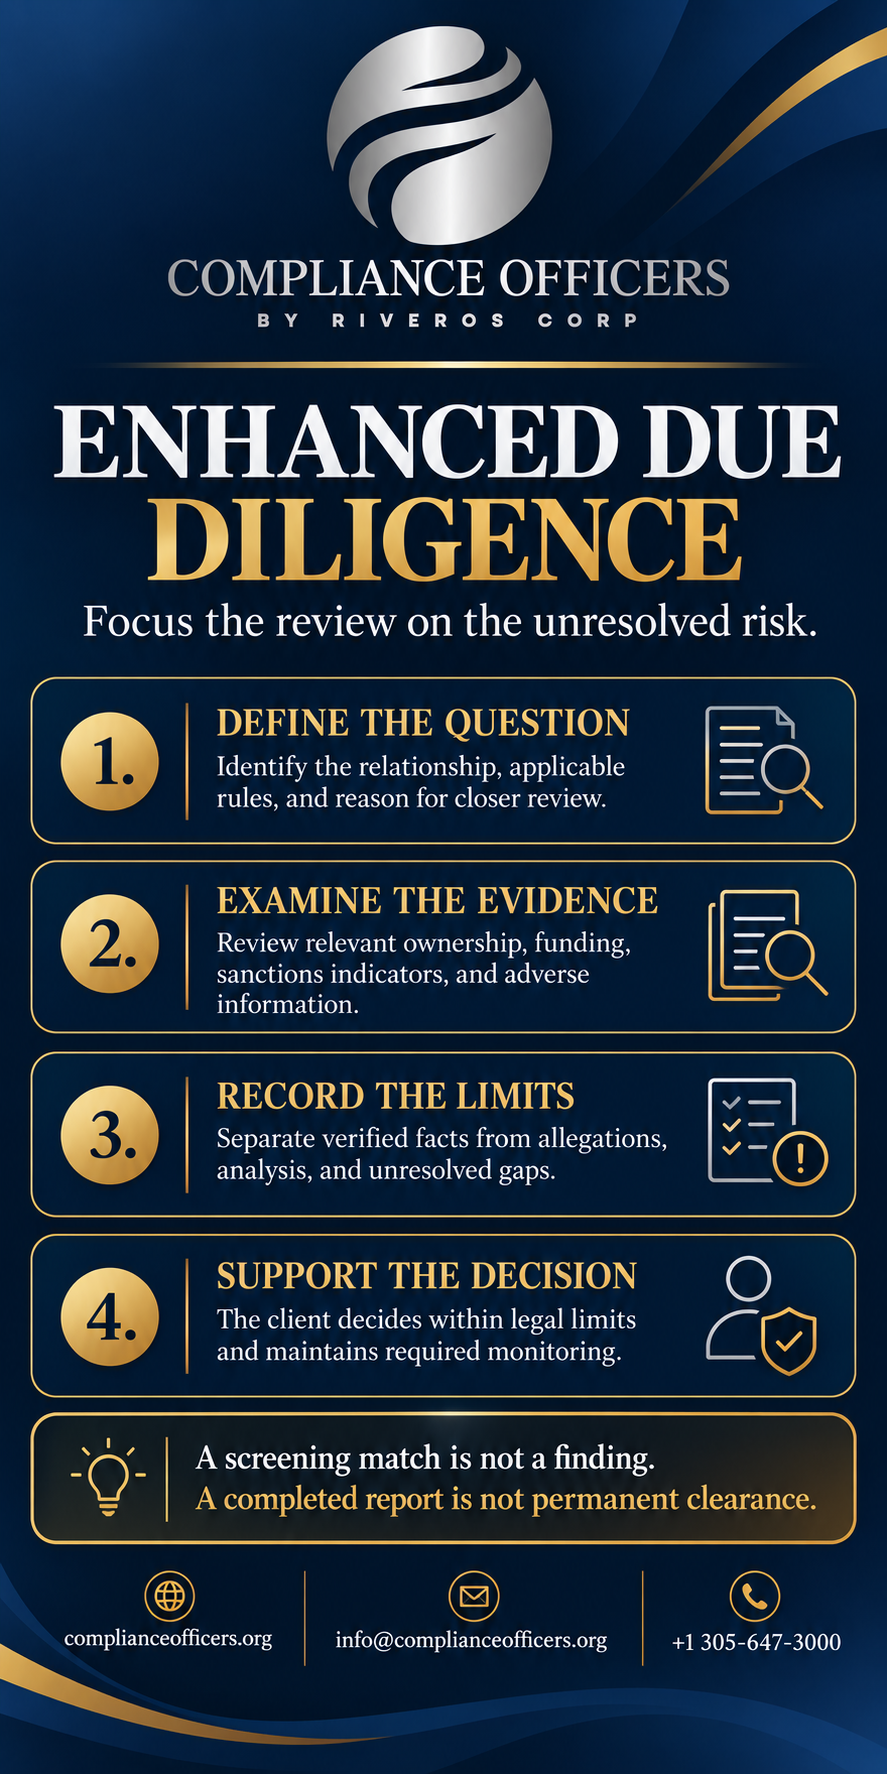
A useful report connects the findings to the reason for the review. It should distinguish established facts, information supplied by the subject, analytical conclusions, and unresolved questions.
Scope matters as well. Identify the subject, jurisdictions, sources, and review period. If a source was unavailable or a material record could not be obtained, explain how that limits the findings.
The report should also make clear who decides what happens next. External research can support a decision, but it does not automatically replace the client’s authorized risk owner or legal adviser.
Possible next steps may include further inquiry, conditions on an otherwise permitted relationship, or declining the engagement. The available choices depend on law and policy. A decision to accept commercial risk cannot override a legal prohibition.
Closing a review does not end monitoring
A defined research assignment can reach a conclusion while the business relationship continues. The client should distinguish closing that assignment from ending any ongoing monitoring duty.
For banks, CDD includes ongoing monitoring and risk-based updates. Material changes in ownership or activity can require renewed attention. There is no universal calendar that fits every customer and institution.
Commercial relationships can also change after onboarding. A new owner, payment route, or service may justify a further review under the company’s policy. The earlier report remains a record of its scope and date, not a permanent clearance.
Our discussion of vendor due diligence addresses these questions in supplier relationships. The relevant review should match the exposure created by the service or transaction.
How Compliance Officers supports the review
Compliance Officers examines available information about the person, company, or relationship in scope. The engagement can cover legal existence, ownership information, public records, sanctions indicators, and relevant adverse information.
First, define the question the client needs to resolve. Then agree on the scope, jurisdictions, and expected deliverable. The research should address that question without promising access to records that may be unavailable or restricted.
Some work can proceed remotely through records and other sources. Operational verification may require additional arrangements. If a physical check or local assistance is necessary, clarify that before treating it as part of the engagement.
Timing and cost depend on the work. Ownership complexity, languages, access to records, and responses from the subject can affect delivery. Request a proposal based on the actual file rather than assuming every review requires the same effort.
Enhanced due diligence: common questions
Is enhanced due diligence mandatory for every company?
No universal EDD rule applies identically to every company. Specific financial-sector rules and broader risk-based obligations can require enhanced measures. Other businesses may adopt additional checks through their risk policies or contractual requirements. Applicable sanctions restrictions remain a separate consideration.
Does a clean screening result complete the review?
No. It answers a limited question about the search performed. Ownership, transaction purpose, funding, or adverse information may require separate examination. The report should state the search scope and date rather than present “no matches” as a general clearance.
Are source of funds and source of wealth the same?
No. Source of funds concerns the money for the transaction or relationship. Source of wealth concerns the accumulation of assets over time. The review should request relevant evidence where those questions matter, rather than assume one explanation resolves both.
Does a PEP match mean the relationship must be declined?
No. Confirm the identity and assess the applicable rules and facts. PEP status does not itself establish a sanctions restriction or wrongdoing. Specific private banking requirements may apply to senior foreign political figures, while other reviews follow their relevant risk-based framework.
Can the work take place remotely?
Many records-based activities can take place remotely. However, verifying operations or obtaining certain local records may require additional work. The engagement should identify those limits and distinguish a completed records review from any physical verification that remains outstanding.
How much time and cost should I expect?
The answer depends on the subject, jurisdictions, ownership structure, languages, and evidence available. A provider should explain the proposed scope and limitations before quoting. Changes in scope or unanswered material questions may affect the estimate.
Discuss the question your current file leaves open
Contact Compliance Officers to discuss an enhanced due diligence review. Identify the counterparty, the proposed relationship, and the issue your existing information does not explain.
Call +1 (305) 647-3000, write through WhatsApp, or email info@complianceofficers.org. We can discuss the research needed and the limits of the available information.
This publication provides general information and does not constitute legal advice, a legal opinion, or a guarantee of acceptance. Requirements depend on the institution, transaction, jurisdiction, and applicable law. Seek qualified legal advice about regulatory duties and potential sanctions restrictions.