What is a 501c3? The term refers to an organization described in section 501(c)(3) of the Internal Revenue Code, commonly called a charitable organization. The section provides a federal tax-exemption framework for qualifying purposes and operations. It does not identify a particular state-law company form or make every transaction tax-free.
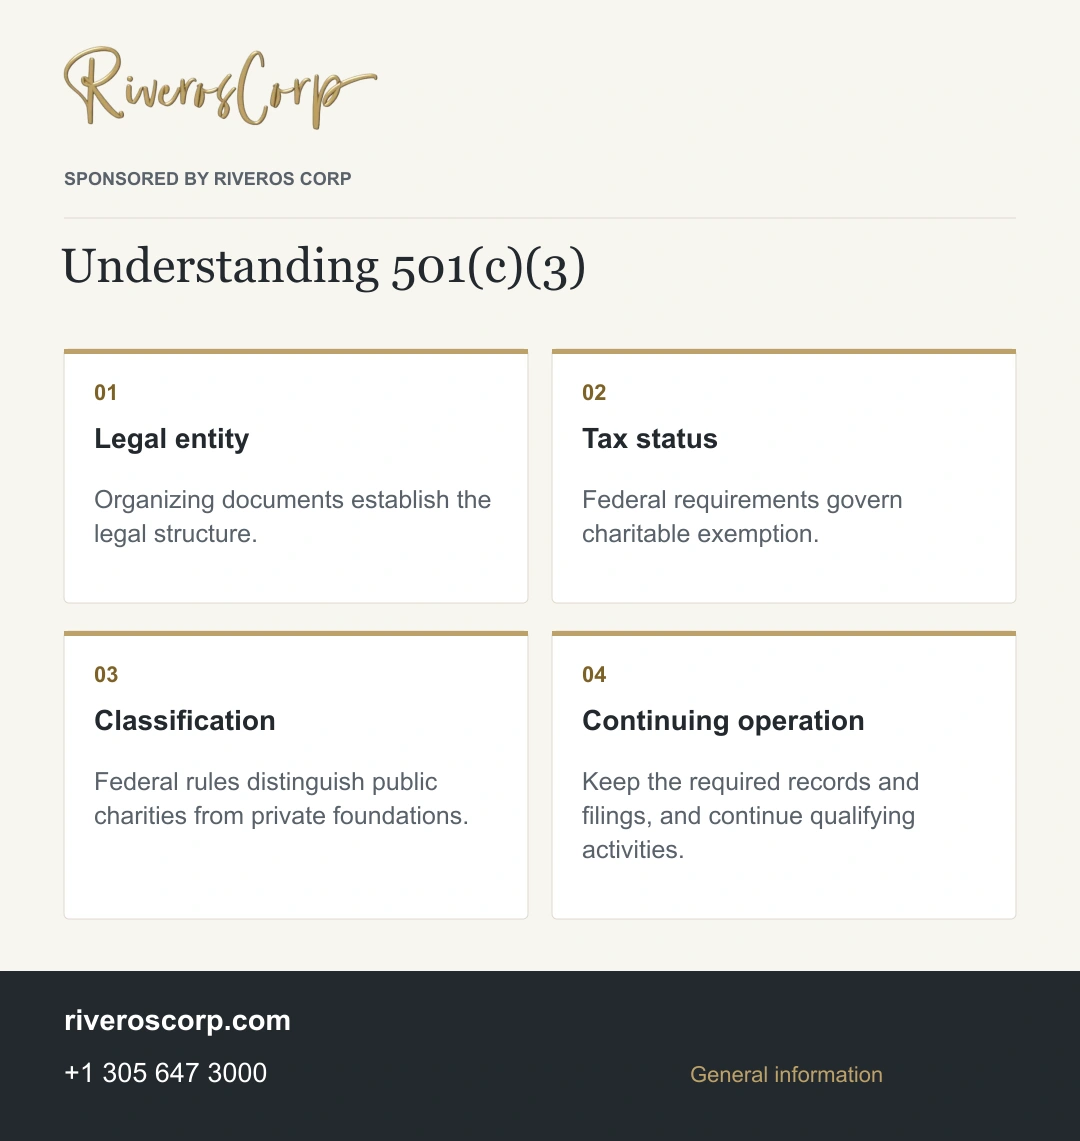
When someone plans to “open a 501c3,” the project usually involves establishing an organization and addressing its federal tax status. Articles, bylaws, an EIN and an IRS determination letter each serve a different function. The documents should identify the same organization; each addresses a separate part of its formation or tax record.
The tax review also depends on the planned work. A charity can receive revenue and pay people for real work while remaining subject to limits on private benefit and the use of its assets. Public charities and private foundations have different rules. Before choosing an application, founders need a clear account of the programs, funding and governance so the proposed tax classification reflects how the organization will operate.
What is a 501c3 under federal tax law?
Section 501(c)(3) covers qualifying charitable, religious, educational and other specified exempt purposes. Scientific and literary purposes are among the statutory categories. An organization must meet both organizational and operational requirements; stating a permissible purpose does not end the analysis.
The organizational test concerns the legal framework established by the organizing document. The operational test looks at what the organization actually does. An entity can have carefully written articles and still conduct activities that do not satisfy the federal standards.
The rules also limit private benefit and prohibit private inurement. These concepts address the use of an exempt organization to serve private interests or divert earnings to insiders. Founders should understand those limits before treating the entity as a business they personally own.
Federal exemption generally concerns income taxation under the applicable rules. It does not make every transaction tax-free or remove every filing requirement. The organization’s particular activities, classifications and locations determine what other obligations need attention.
Nonprofit status and 501(c)(3) status differ
“Nonprofit” commonly describes an organization established under state law without the ordinary profit-distribution structure of a business corporation. Section 501(c)(3) describes a federal tax category. An organization can be a state nonprofit without qualifying under that federal provision.
There are also federal exemption categories other than section 501(c)(3). A social club or business association may raise a different classification question from a public charity. Choosing a state nonprofit form does not automatically identify the correct federal category.
An EIN is another separate matter. It identifies the entity for federal tax administration. Its issuance does not constitute an exemption determination, even if the organization selected a nonprofit description when obtaining the number. Our article on what an EIN means explains this distinction.
Use precise language when discussing a new organization. “Incorporated,” “application pending” and “recognized by the IRS” describe different facts. Public statements and fundraising materials should not collapse those stages into an unsupported claim that every approval has already been obtained.
Public charities and private foundations
Section 501(c)(3) organizations are classified as public charities or private foundations. The private-foundation classification generally applies unless the organization qualifies for an exception under section 509(a). This is a federal classification question, not simply a choice of wording in the organization’s name.
Public-charity categories include certain institutions, such as churches and schools, as well as organizations satisfying particular support or relationship tests. Many public charities receive support from varied sources. Their actual classification must fit the relevant requirements rather than a general impression of being open to the public.
Private foundations often receive support from a family, company or other concentrated source, and many make grants. Those are common characteristics rather than a complete legal test. Some foundations operate their own programs, so activities and funding should be evaluated carefully.
The classification affects annual reporting and other tax rules. An organization supported mainly by one family cannot establish public-charity status merely by naming itself a public foundation. Conversely, the word ‘foundation’ in a name does not settle its IRS classification. The support sources, activities and applicable section 509(a) category need to be examined together.
Can a 501(c)(3) earn revenue?
Yes. A charitable organization can receive donations, charge for appropriate services and earn other revenue. It can also have resources left after paying expenses. The key questions concern its purposes, activities, use of funds and compliance with the applicable rules.
A surplus is not automatically a problem, and an organization need not end every year with an empty bank account. Reserves can support future operations. However, the existence of a surplus does not authorize distributing charitable earnings to founders as personal profits.
Payments for genuine services are different from ownership distributions. Reasonable compensation may be permitted, but the arrangement must be assessed properly. The amount, duties, approval process and relationships involved can matter, particularly when a leader or related person benefits.
Payment records should identify the service, the person who performed it and who authorized payment. Calling a payment a stipend does not establish that it is reasonable compensation. Similarly, a reimbursement needs records of the underlying expense. These details let the organization and its tax adviser evaluate what happened without relying on a label in the bank statement.
Commercial income can require a separate tax review
An exempt organization may have unrelated business income when it regularly conducts a trade or business that is not substantially related to its exempt purpose, subject to applicable exceptions and modifications. Directing the resulting money toward charity does not by itself make the underlying activity related.
The exceptions depend on the facts. A business in which substantially all work is performed without compensation is excluded from unrelated trade or business. There is also an exclusion for selling merchandise received substantially entirely as gifts or contributions. Those conditions matter: describing a staffed retail operation as fundraising does not establish that either exception applies.
Before adding a substantial revenue-generating program, describe the proposed activity to the appropriate tax adviser. Explain who performs the work, whom it serves and how it relates to the mission. Review should consider both possible tax obligations and the effect on the organization’s exempt operations.
Maintain records that distinguish activities clearly enough for the applicable reporting. Combining every receipt under a single description such as “fundraising” can hide important differences. The accounting should help explain the organization’s operations rather than obscure them.
Restrictions affect how the organization operates
Charitable assets must serve the organization’s exempt purposes. A founder cannot assume unlimited control over those assets simply because they created the organization. Governing documents, fiduciary obligations and federal tax restrictions all need consideration when decisions benefit insiders.
Section 501(c)(3) also restricts lobbying and political campaign intervention. Lobbying and campaign activity are different subjects under the rules. Some charities may conduct limited lobbying within the applicable framework, while the statutory restriction on intervention in candidate campaigns is separate.
For houses of worship, an April 3, 2026 Treasury announcement described planned guidance on certain internal faith-related communications. It also described a government litigation position that the court had not approved before dismissing the case for lack of jurisdiction. That development should not be read as permission for all charities to support candidates. A proposed communication or expenditure needs review under the rules applicable when it occurs.
These limits should inform the decision to seek charitable status. If the founders’ central objective is private ownership returns or activities inconsistent with the exemption, another structure or classification may need consideration. Changing the mission statement’s vocabulary does not resolve a substantive mismatch.
How an organization seeks recognition
Most organizations seeking section 501(c)(3) recognition apply through Form 1023 or, if eligible, Form 1023-EZ. The streamlined form has a required eligibility worksheet. Its exclusions address more than financial size, including legal structure, activities and organizational history.
The organizing documents should be reviewed before the application. A corporation’s articles need to satisfy the relevant federal requirements, including appropriate purpose limitations and dedication of assets. See our explanation of 501(c)(3) articles of incorporation requirements for the role of that document.
Bylaws and governance records serve related but different functions. They should fit the organization and the law rather than repeat provisions from an unrelated template. A full application also needs an accurate description of activities and other requested information.
There are exceptions to the recognition-application requirement. Churches meeting the federal standards are a familiar example, but a name alone does not establish church classification. Whether an exception applies should be assessed before an organization relies on it in public statements or financial planning.
Donations, recognition and public information
Many section 501(c)(3) organizations are eligible to receive tax-deductible contributions under the applicable rules. Eligibility at the organization level does not guarantee a deduction for every donor or payment. The gift, any benefits received and the donor’s documentation all matter.
A determination letter can help explain an organization’s recognized status, but it should be read for the correct entity and classification. An EIN confirmation or a state certificate is different evidence. Avoid presenting one document as though it answers every possible status question.
Approved exemption applications and related materials generally become subject to public-inspection requirements, with specified exceptions. Many annual information returns are public too. Identify the records subject to disclosure and keep an accessible copy. The public version should follow the applicable redaction rules; an organization should not remove required information simply because it would prefer to keep it private.
Absence from an IRS search result requires careful interpretation. Some qualifying churches and organizations covered by group arrangements may not appear separately. A reviewer should identify the legal organization and the relevant documentation rather than draw a conclusion from a name search alone.
What continues after recognition
Most exempt organizations have annual information-return or notice obligations, with exceptions for certain categories. The appropriate filing can depend on classification and financial circumstances. A prior year’s filing choice should not be repeated without checking whether the relevant facts changed.
Failure to file a required annual return or notice for three consecutive years results in automatic revocation. This rule concerns organizations that are required to file; it should not be applied as though every church has the same annual-return obligation.
State corporate reports, fundraising rules and state taxes remain separate matters. An IRS determination does not replace those requirements. A leadership transition should include access to official correspondence, financial records and the calendar of continuing obligations.
For churches and ministries, Riveros Corp offers 501(c)(3) document preparation, including bylaws, policies, minutes and application materials based on the organization’s information. Its administrative support should reflect decisions the organization has actually made. Legal classification, tax treatment and disputed governance questions require the appropriate licensed professional; the document service does not decide those issues.
Frequently asked questions
What does having 501(c)(3) status mean?
It means the organization qualifies under a federal charitable tax-exemption provision, subject to continuing requirements. It does not mean every transaction is tax-free, every payment is deductible or every state registration has been completed.
Can a 501(c)(3) pay employees or its founder?
Reasonable compensation for actual services can be permitted. The arrangement needs appropriate review, authorization and records, particularly for insiders. Compensation is different from distributing profits to someone merely because they founded or control the organization.
What are the disadvantages of seeking this status?
The organization accepts limits on private benefit, political activities and the use of charitable assets, along with reporting and disclosure obligations. Those commitments may not suit a project whose purpose is private ownership returns. Assess the intended activities before choosing the structure.
Is every nonprofit a 501(c)(3)?
No. State nonprofit status and federal exemption are separate. Some nonprofits qualify under other federal provisions, and some have not established federal exemption at all. An EIN or accepted incorporation filing does not itself establish section 501(c)(3) status.
Does an approval letter last forever?
Recognition depends on continuing qualification. Changes in activities, inaccurate information or failures to meet applicable obligations can affect status. Organizations required to file annual returns or notices face automatic revocation after three consecutive years of nonfiling. Relevant filing exceptions must be considered.
Discuss your charitable organization documents
Contact Riveros Corp at +1 305 647 3000 to discuss your document preparation needs. Bring the formation records, any IRS correspondence and a description of the intended activities so the request can be assessed accurately.
General information, not legal or tax advice for a particular situation. By Zulma E Bourelly.