Does an ITIN expire? Yes. An Individual Taxpayer Identification Number generally expires after it has not been used on a federal income tax return for three consecutive tax years. Whether you need to renew it now depends on how you will use it, not simply on how long you have had the number.
Someone who needs an ITIN on an upcoming federal return faces a different situation from someone whose number appears only on an information return. A person who has become eligible for a Social Security number also needs a different review. Renewing an ITIN without checking those facts can create unnecessary work or leave the underlying tax identification issue unresolved.
Start with your IRS assignment notice and the relevant tax returns. Those records help establish which number was issued, how it was used and whether renewal is necessary for the filing you are preparing.
When renewal is needed, the applicant uses Form W-7 to renew the expired number.
Does an ITIN expire after three years of nonuse?
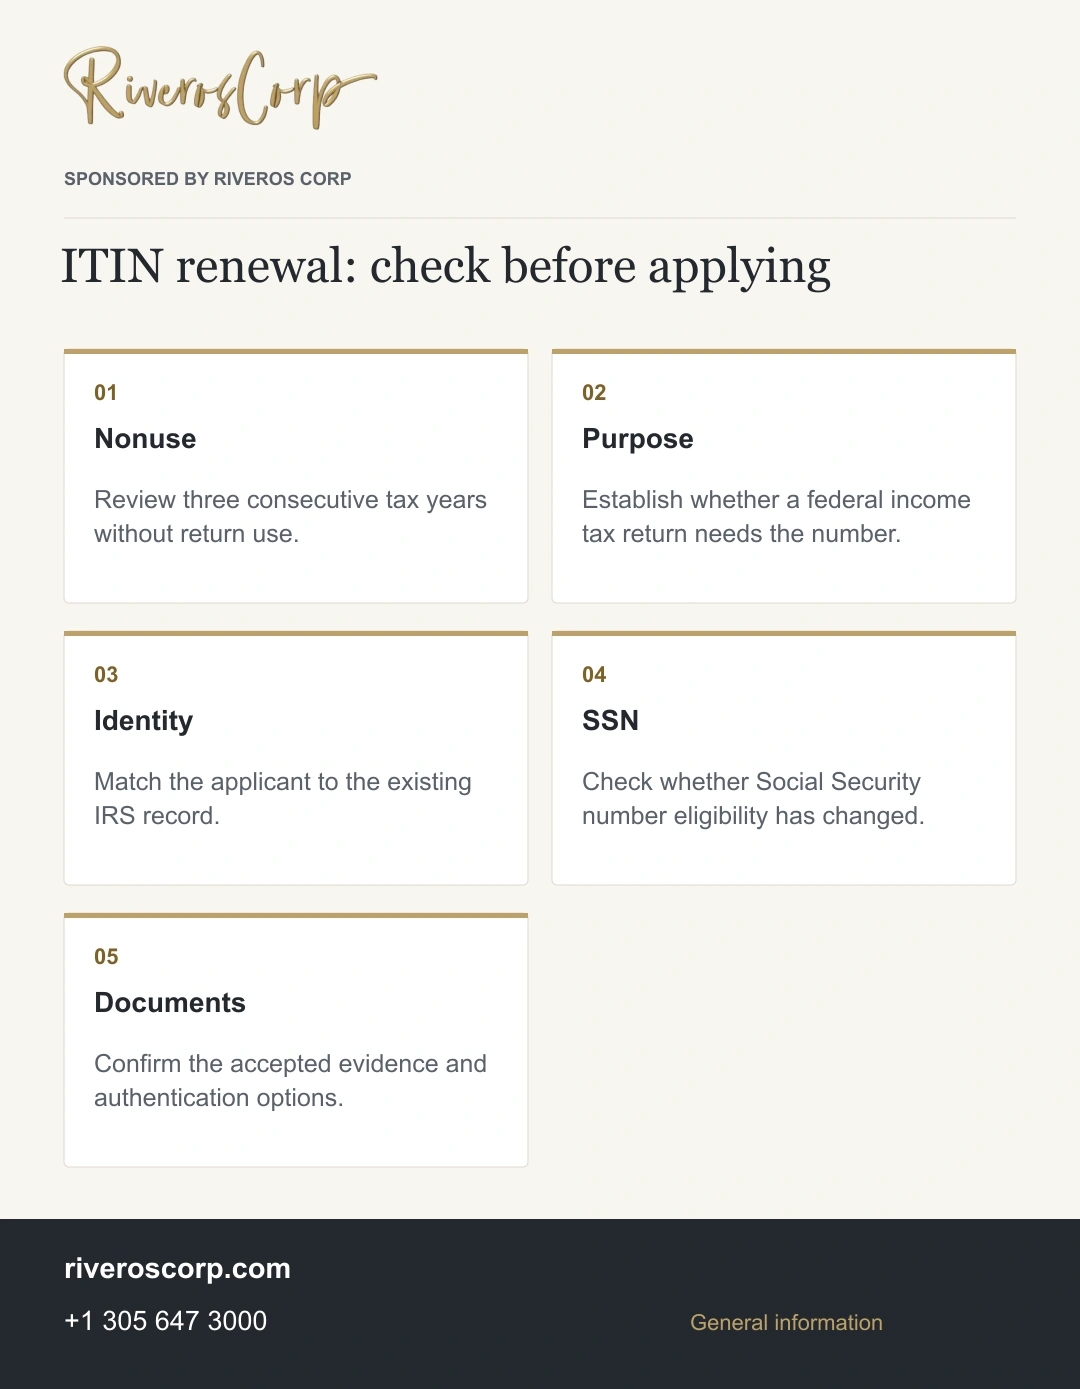
The general nonuse rule looks at three consecutive tax years without use on a federal income tax return. The number expires on December 31 following that period. The rule concerns use on a federal income tax return. A bank profile or business document does not show that use.
This distinction matters when a person says, “I still use my ITIN.” They may mean that a financial institution retains it, even though it has not appeared on a federal income tax return during the relevant years. A review should therefore identify the actual returns rather than relying on memory or a current account statement.
The IRS also addresses certain older ITINs issued before 2013 that were never renewed. Old articles about particular middle-digit groups should not be used as a current renewal calendar. The present filing situation and current IRS instructions are the appropriate starting points.
Expiration does not erase the original number or tax history
An expired ITIN does not mean that the IRS has deleted the taxpayer’s previous returns. Renewal concerns the number’s current validity for the relevant tax purpose. It is not a request to start a new tax identity or abandon an existing filing history.
Someone who already has an ITIN should disclose that fact when preparing renewal documents. Applying as though no number had ever been assigned can create confusion. The prior assignment notice, IRS correspondence and copies of previously filed returns can help a preparer identify the record correctly.
An ITIN also remains a tax identification tool. It does not establish immigration status, authorize employment or provide Social Security benefits. Its renewal does not change those limitations. Our explanation of an ITIN tax ID for foreigners discusses the role of the number separately from immigration and employment documents.
Check whether renewal is needed for the upcoming return
The IRS directs taxpayers with expired ITINs to renew when they need the number on a federal income tax return. Renewal is not automatically necessary simply because a person owns an expired number. The intended filing and the reason the person needs the ITIN must be established first.
For example, an ITIN used only on certain information returns does not have the same renewal requirement as an ITIN needed for a federal income tax return. The IRS specifically distinguishes information-return-only use in its renewal guidance. A taxpayer should not assume that receiving a tax document means the number must immediately be renewed.
A preparer can review the person’s filing obligation and explain which documents require a valid ITIN. That review should precede gathering documents for an application. It also helps identify whether the person now needs a Social Security number or another type of taxpayer identification instead.
Review each family member’s situation separately
Each family member needs a separate renewal review. A spouse or dependent must meet the applicable ITIN requirements and have the relevant federal tax purpose. Merely wanting a number for general identification is insufficient.
The IRS instructions contain particular rules for spouses and dependents, including requirements connected with an allowable tax benefit or their own return. Supporting documentation may also differ. A passport that resolves one applicant’s documentation needs may not establish every fact required for a dependent’s application.
Keep the review individual. Record whose number was issued, where it appeared on prior returns and why it is needed now. This is especially important after changes in household circumstances, residency, marital status or eligibility for a Social Security number. A family’s earlier application package should not be copied into a new filing without checking what has changed.
What records help establish whether an ITIN expired?
Useful records include the original IRS assignment notice, renewal correspondence and copies of federal income tax returns for the relevant years. A list of filing years is helpful, but the returns themselves provide a better basis for checking how the ITIN appeared.
Distinguish a prepared return from one actually filed. A draft saved on a computer does not show that it reached the IRS. Where filing or processing is uncertain, a qualified tax professional can determine which IRS records or follow-up steps are appropriate. Avoid assuming that an unanswered application or an unfiled draft established a valid number.
Name differences also deserve attention. If a passport, prior return and IRS notice use different names, retain the records explaining the difference. Do not alter original documents to make them appear consistent. The application should accurately connect the applicant’s identity with the existing tax record.
Renewal generally uses Form W-7 and supporting evidence
Form W-7 is used for ITIN applications and renewals. A renewal package generally includes the applicable federal tax return unless an exception applies, together with the required identity and foreign-status documentation. The appropriate package depends on the facts and the current instructions.
An exception should be supported by the documentation required for that exception. It is not enough to label an application “exception” to avoid attaching a return. Similarly, a photocopy of an identity document is not automatically an acceptable replacement for the original or an issuing-agency-certified copy.
Our overview of the ITIN application process explains the purpose of the supporting records. The renewal review should preserve the existing ITIN and tax history while establishing the applicant’s current eligibility. The IRS makes the determination; assistance preparing a package does not guarantee acceptance or a particular processing date.
How a CAA handles renewal documents
The way you apply determines who reviews the identity documents. The IRS accepts applications directly and through authorized acceptance agents. Designated IRS Taxpayer Assistance Centers also offer document authentication by appointment. A Certifying Acceptance Agent, or CAA, can authenticate permitted documents and return them after review; an ordinary Acceptance Agent forwards the required originals or issuing-agency-certified copies to the IRS.
For a primary applicant or spouse, a CAA can authenticate the accepted identity documents except a foreign military identification card. For dependents, its authentication authority covers passports and birth certificates. If another document is needed, the application still needs that document in the form the IRS accepts. Certification of a passport does not establish a dependent’s residence when separate residence evidence is required.
Riveros International Business Corp appears in the IRS Florida directory as a Certifying Acceptance Agent. For an ITIN renewal, the team can review the permitted identity documents, prepare the W-7 package and handle application correspondence within that role. Explain any planned travel before arranging document delivery, since the CAA needs access to the document it will authenticate.
If you have obtained a Social Security number
A person who has received a Social Security number should not continue using an ITIN in place of that number or renew the ITIN as though nothing changed. The IRS provides procedures for notifying it so the tax records can be associated correctly.
Keep evidence of the Social Security number assignment and the former ITIN. A preparer can explain the appropriate notification and how to handle the next return. Use the SSN consistently and connect the former ITIN record to it through the IRS notification process.
Eligibility for a Social Security number also matters before renewal. An ITIN is generally for someone who needs a federal taxpayer identification number and is not eligible for an SSN. If work authorization or another circumstance has changed, review eligibility before treating ITIN renewal as the automatic next step.
An expired ITIN can affect return processing
Using an expired ITIN on a return can delay processing and affect the treatment of certain claimed tax benefits until the identification issue is resolved. A taxpayer should not assume that filing first and dealing with renewal later will leave the return unaffected.
At the same time, expiration does not remove filing obligations or make tax deadlines disappear. Someone approaching a deadline needs a qualified professional to review filing, renewal, extension and payment questions together. Those are related tasks, but completing one does not necessarily satisfy the others.
Keep copies of the submitted package and correspondence, and track requests for additional information. If the IRS asks for a missing item, respond through the appropriate channel with the requested evidence. Repeatedly submitting new applications without understanding an outstanding notice can make the record harder to follow.
Bring your filing history to the renewal review
Before contacting the team, identify the last tax years in which the ITIN appeared on filed federal returns. Keep the assignment or renewal notice and any later IRS correspondence with those returns. If the number belongs to a spouse or dependent, identify the return on which it appeared and the current tax purpose for including that person.
Riveros Corp’s ITIN application and renewal service includes W-7 preparation and CAA document certification. The review needs to distinguish an expired number from a rejected application or a number already replaced by an SSN. Those situations require different records, even if the immediate request sounds the same: help obtaining a usable tax identification number.
Use the agreed document process to send identity and tax records. An initial inquiry can describe the filing years and type of IRS notice without exposing a full ITIN or passport image. Once the team identifies the records needed, provide complete copies rather than cropped fragments that omit the applicant’s name, tax year or the explanation in a notice.
Frequently asked questions
Does an ITIN expire if I still have the assignment letter?
Yes. Possessing the original letter does not prevent expiration under the nonuse rule. The letter remains useful evidence of the assigned number, but validity depends on the applicable IRS rules and use on federal income tax returns. Review the relevant filing years rather than the condition or age of the paper.
Do I receive a different number when I renew?
Renewal concerns an existing ITIN. It should not be approached as an application for an unrelated new tax identity. Include the existing number and required information in the appropriate renewal process. Keep prior notices so the IRS record can be identified consistently.
Must I renew an ITIN used only for information returns?
The IRS states that an expired ITIN used only on information returns does not need renewal for that use. If the number will also be needed on a federal income tax return, review the renewal requirement separately. A financial document alone does not resolve that distinction.
Can ITIN renewal provide permission to work?
No. An ITIN is a tax processing number. Applying for or renewing it does not establish lawful immigration status or employment authorization. Questions about work authorization belong with an appropriately authorized immigration professional, even when the person also needs help with federal tax records.
Does an expired ITIN cancel my tax filing deadline?
No. The need to renew does not remove a filing obligation or postpone a deadline. The IRS also says an ITIN is not required to request an extension or make estimated tax payments. Have the return preparer consider those obligations together with renewal, particularly when the filing date is close. An extension to file does not itself extend the time to pay.
Review your ITIN document needs
Contact Riveros Corp at +1 305 647 3000 or through WhatsApp for ITIN renewal and CAA document certification. Have your ITIN notice, relevant filing years and any IRS correspondence available. Questions about the return’s tax treatment can be reviewed with the professional preparing that return.
By Zulma E Bourelly. General information only. Individual legal and tax questions require advice from an appropriately qualified professional.